Demand at reservation. Scale by design.
The global build-out of data infrastructure is not limited by demand — it is
limited by supply. A reported pipeline above 5 GW in Malaysia alone. Gigawatts of
committed national capacity in Australia. A multi-trillion-yen hyperscaler building
wave across Japan. The largest power-interconnection queue in history forming in
Texas. Vacancy at record lows across Europe’s core hubs. Every one of those markets
is searching for the same thing: capacity that can be delivered faster, at lower
cost, and with a fraction of the carbon. That is precisely the constraint Serene DC
removes.
01 — Deposit at reservation
Demand starts before construction does
Growth at Serene DC is funded by its own order book. Customers reserve vault capacity
before it is built, committing a 15% completion deposit at reservation — returned at
completion, or rolled into the next reservation, and funding the long-lead production forms
and casting capacity each new region requires. Expansion is not financed on projections.
It is financed on contracted demand.
02 — Speed is the multiplier
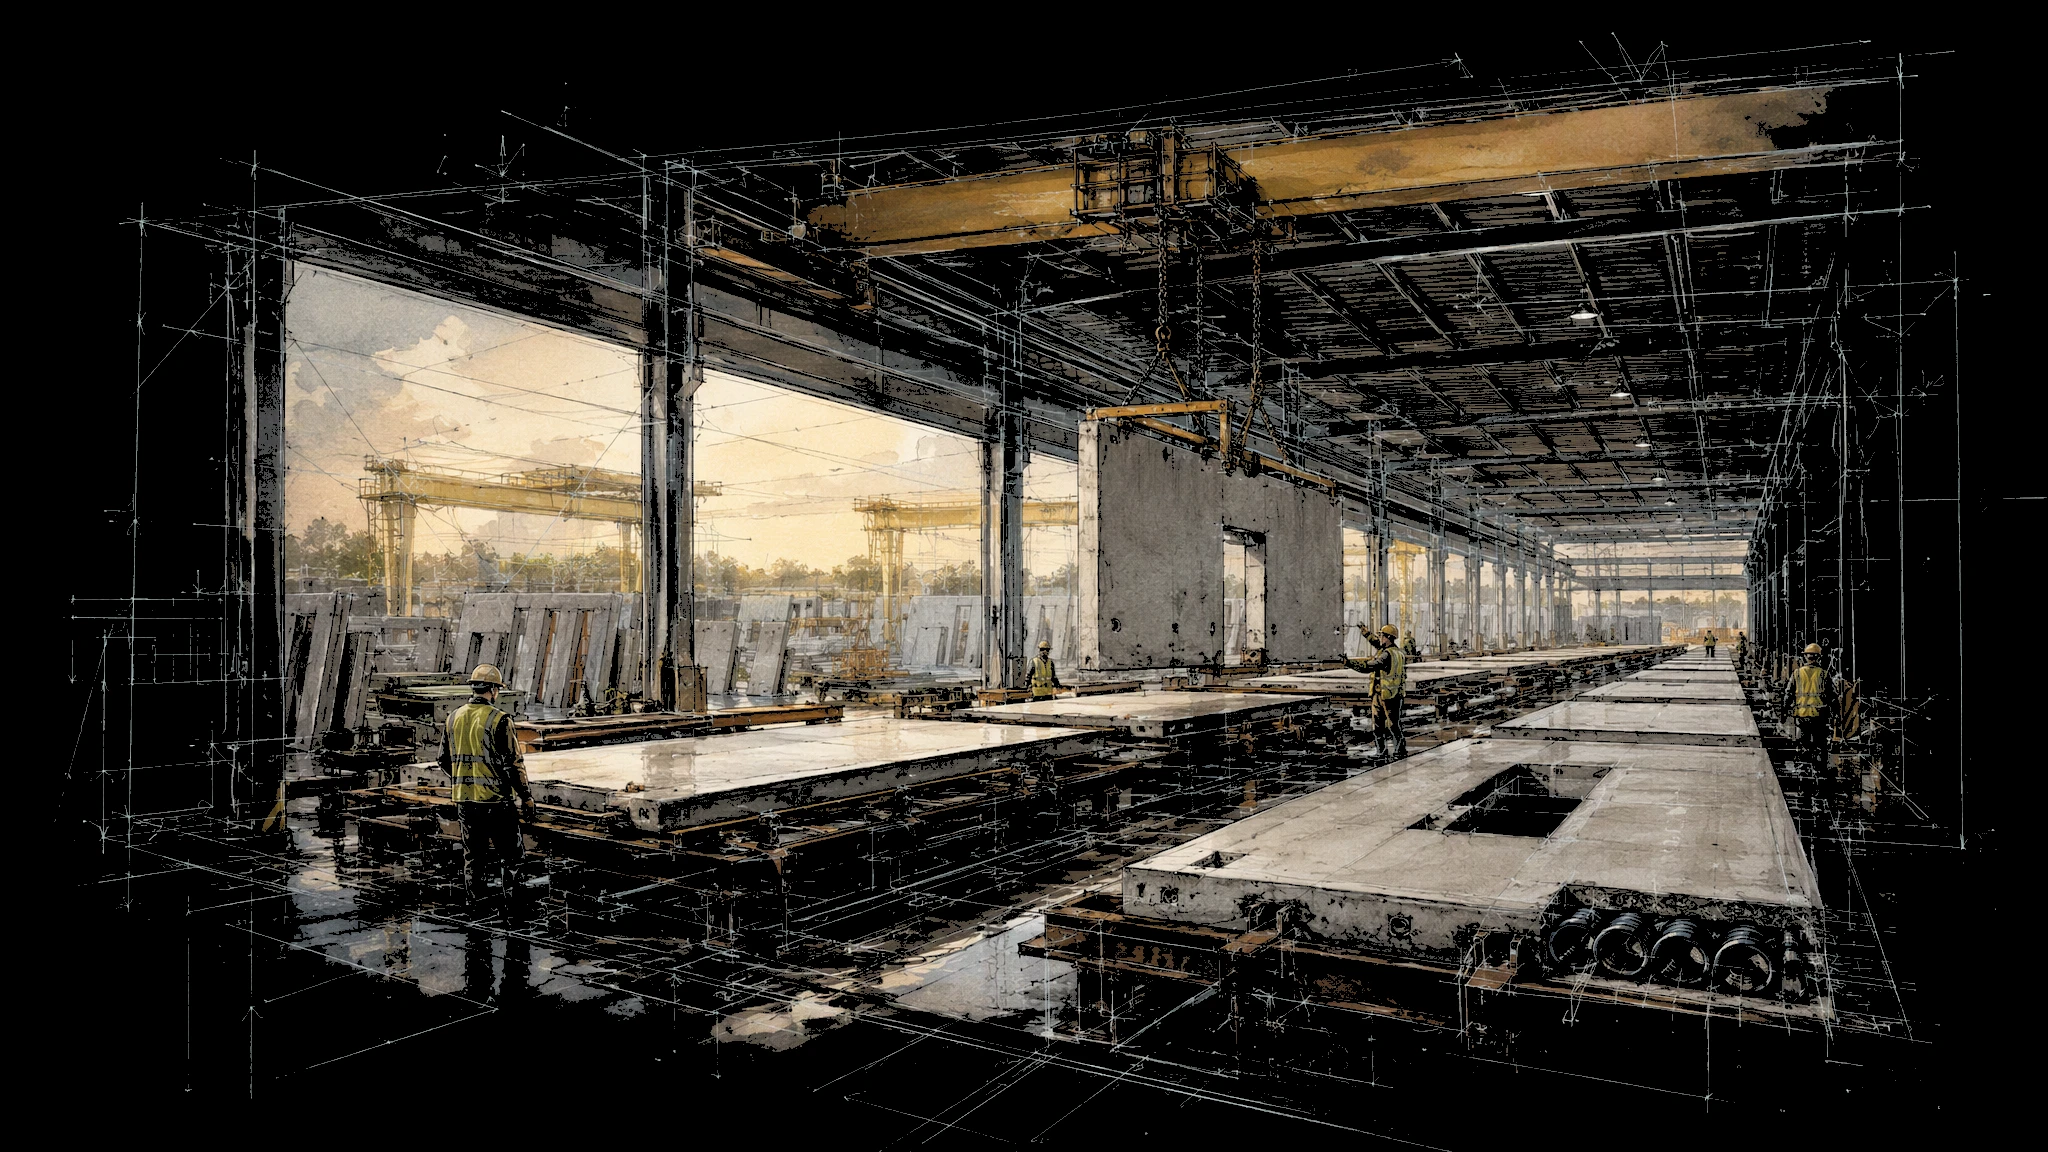
A manufacturing system, not a construction project
Conventional facilities are poured in place and cured for weeks. Serene DC
vaults are cast in regional toll-manufacturing depots, cured in hours, and
assembled by crane line in days. The model replicates cleanly: establish a depot
near feedstock and demand, and an entire market’s supply comes online at once.
Speed is not a project attribute — it is the manufacturing system, and it
compounds with every region added.
03 — Margin is the fuel
Strongest where building costs most
With up to 60% lower capital cost and 55% lower operating cost than conventional
construction, Serene DC competes hardest where building is most expensive. The
margin map leads with Japan and the Nordics — premium build-cost capitals where
the structural cost advantage is worth the most, and where low-carbon power and
sovereign buyers reward the material’s credentials. Margin is not the outcome of
the model; it is the fuel for the next depot, the next region, the next market.
04 — The compounding map
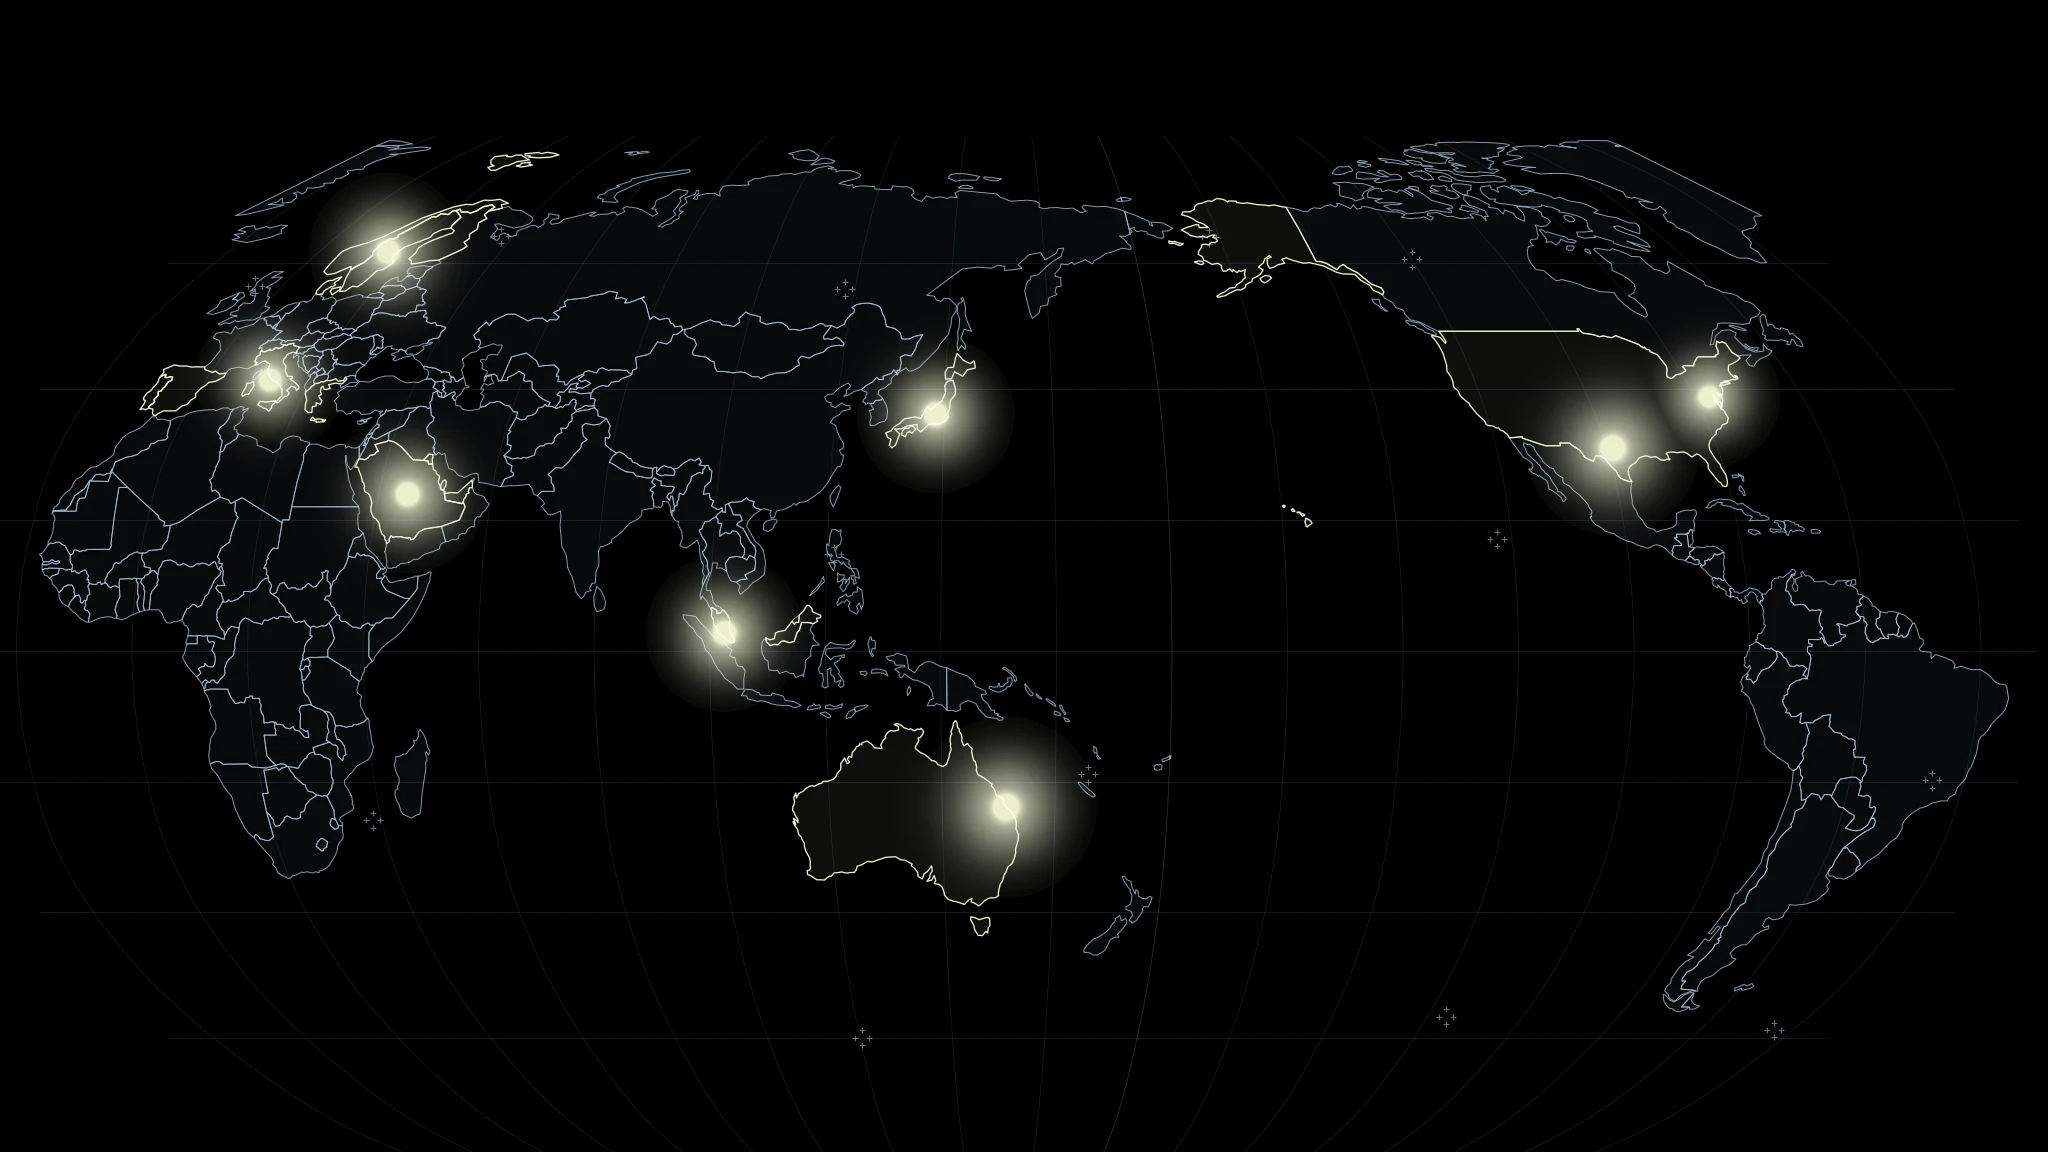
Three theatres, one manufacturing model
Each theatre is entered where the economics are strongest, and each new depot
lowers the cost of the next.
APAC
The founding casting depot sits in Gladstone, Australia, beside the heavy
industry that feeds it. Japan’s metros follow, riding a multi-trillion-yen
hyperscaler build. Malaysia’s 5 GW-plus pipeline and Australia’s own
gigawatts of committed national capacity complete the fastest-growing
theatre on earth.
USA
Texas, where more than 200 GW of large loads sit in the largest
power-interconnection queue in history — and northern Virginia’s outer ring,
as the world’s largest data centre market expands outward.
EMEA
The Nordics, where abundant low-carbon power meets premium pricing; the
emerging hubs of Southern Europe; and the Gulf, where sovereign-backed
demand is building at national scale.
The momentum, quantified
5 GW+
Reported development pipeline — Malaysia alone.
¥2.26 trillion
A single hyperscaler’s committed build programme in Japan.
200 GW+
Large loads queued for power connection in Texas — the largest queue in history.
Record lows
Vacancy across Europe’s core data centre hubs.
15%
Completion deposit at reservation — returned at completion or rolled into your next reservation
60% / 55%
Lower capital and operating cost than conventional construction.
Hours
Cure time for structural panels — not weeks.
3 theatres
APAC, the USA and EMEA — one manufacturing model.
The next five years are contracted demand looking for supply.